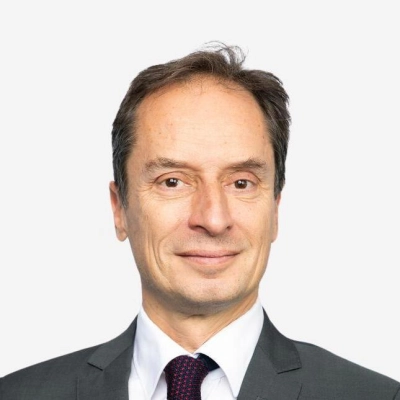
“Understanding the tax rules is only half the job. The real value comes from knowing how the business operates, where the risks lie and how tax advice can shape better commercial decisions.”
Jérôme Labrousse Tax Partner, Forvis Mazars France

Tax governance in commercial decision-making
The move from back-office, retrospective compliance and reporting unit to a proactive, data-driven strategic adviser is vital. Rather than focusing narrowly on returns and compliance or building complex structures solely to pursue tax savings, tax teams need to understand how the business works: where it operates, how it earns revenue and how money moves between entities. Cash flow is one practical place to start. Companies need visibility into payments such as interest, dividends and royalties, and a clear understanding of how those flows work across the group.
At the same time, tax teams still need to preserve valuable attributes, such as research and development credits, understand interest limitation rules, and assess how structural reorganisation or acquisitions could affect losses and other tax benefits. The challenge is to connect that technical work to the company’s wider plans.
“Understanding the tax rules is only half the job. The real value comes from knowing how the business operates, where the risks lie and how tax advice can shape better commercial decisions.”
Jérôme Labrousse Tax Partner, Forvis Mazars France
For CFOs, that means involving tax early in decisions about investment, restructuring and growth. It also means ensuring the tax team can explain how its advice affects forecasts, risks and cash flows. The broader aim is for tax to become a partner in business decisions: compliant and transparent, while helping the organisation understand the consequences of its choices.
Uncertainty has become one of the defining challenges for tax teams. Rules that once seemed relatively stable can now shift with geoeconomic tensions and changing government priorities. For tax teams making decisions with long-term consequences, that makes it harder to predict what the regulatory landscape will look like even a few years from now.
The changing international tax environment adds another layer of complexity. As countries develop their own approaches to regulations such as Pillar Two, companies may face different versions of minimum-tax requirements, with varying obligations and data needs. A framework intended to address the tax planning of very large multinationals can also reach relatively smaller organisations, bringing new reporting duties and compliance costs.
When policies change frequently, companies cannot rely on yesterday’s assumptions to guide tomorrow’s decisions. Tax leaders must consider not only what rules apply today, but how quickly they could change and how prepared the organisation would be if they did.
“Confidence does not necessarily come from certainty. It comes from understanding where changes in tax policy could affect the business and having the information, people and processes in place to respond before those changes become urgent.”
Partner, Forvis Mazars in the U.S.
With uncertainty the new norm, organisations need to build the capacity to respond. That starts with understanding which rules apply, what information is required and where it sits within the organisation. From there, tax teams can establish repeatable processes, use automation where it helps and prepare for likely scenarios before they become urgent.
Confidence to deal with risk and regulatory constraints need not depend on a predictable tax system, and increasingly, it comes from an organisation’s ability to anticipate change and act on it. In an environment where tax policy may shift quickly, preparedness does not guarantee change will be easy - it helps ensure that when the rules move, the business isn't starting from scratch.
As international tax rules grow more complex, companies face more than just understanding new requirements. It is also about producing the right information, reliably and on time.
Tax and finance departments often have limited resources. New obligations can require teams to gather information from multiple sources, reconcile records and meet reporting requirements that may differ by jurisdiction. Companies need to define the scope of what applies to them before deciding how to manage the work. Only then can they build processes that are efficient enough to repeat.
That work may include automation, but technology is not a substitute for sound governance. In particular, organisations need to know who owns each process, whether the underlying information is reliable and how quickly an issue can be escalated. Technology can create capacity, but it should be treated as a tool and not the final authority on a tax position.
In addition, the risks of public disclosure are rising. Companies need to understand what information is being made public and how it may affect the business. If data appears across different filings or platforms, inconsistencies may draw attention from authorities or create a misleading picture. Strong data governance can help organisations maintain a consistent account and identify gaps before they become problems. Good working relationships with finance, accounting, legal and operations teams help ensure tax has relevant information early enough to identify potential problems.
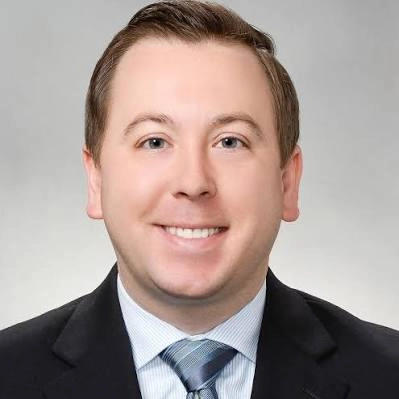
“The time to discover gaps in your tax data is not when the authorities come asking for it. Tax leaders need to know what information is required, where it sits and whether they can rely on it so they can meet regulatory obligations and respond to scrutiny with certainty.”
Eric Flueckiger Partner, Forvis Mazars in the U.S.
It means data readiness is partly a technical challenge and partly a relationship challenge. Teams need systems that can collect and organise information. But they also need access to the people who understand how the business operates. A tax leader who is included in planning discussions can help identify consequences before a decision is finalised.
In a fast-changing regulatory environment, the ability to pivot without reorganising the entire tax function each time business conditions or risks shift offers a clear benefit. But what practical steps can CFOs and heads of tax take to embed the agility now required?
Firstly, agility does not mean reacting to every headline. Much depends on the foundations built before a change occurs: reliable data, strong internal relationships and a clear understanding of how the business works. When tax leaders know what operations, finance, sustainability and legal teams are planning, they are better positioned to identify consequences early and help shape the response.
Tax leaders also need clarity about who owns key processes, whether the information supporting a tax position is dependable and how quickly a developing issue can be escalated. Those questions matter most when a company must defend a position, implement a new requirement, or respond to a sudden change.
Technology can help teams create capacity, but it does not remove the need for judgement and oversight. People who can assess what the information means and determine when an issue requires attention are essential.
External relationships are equally important. The pace of change makes it difficult to rely on occasional updates or annual compliance routines. Building more proactive relationships with industry associations, peers and trusted advisers can help keep abreast of changes and promote a forward-thinking approach. Rather than waiting until a new law creates an urgent compliance request, getting insights into how emerging regulations and political developments could affect the business can reveal what information will be required and whether the company already collects it.
This kind of preparation can make an organisation more responsive. If a future rule depends on data that is not currently available, the company can consider collecting it before it becomes essential. If a policy changes, leaders who have already discussed possible impacts may be able to act faster.
It’s equally important to understand the reasoning behind rule changes to move from anticipation to adaptation and action. That mindset helps prevent teams from spending too long reacting emotionally to developments they cannot control.
For heads of tax, the priorities are clear: remain curious, maintain regular dialogue with external advisers and peers, and stay closely connected to colleagues inside the organisation. Agility is not a last-minute response but a capability built through ongoing preparation so that when change arrives, the business is ready to move.
European tax policy is evolving, but companies should not assume that proposals such as the European Commission’s Tax Omnibus proposal, which aims to “simplify”, will immediately reduce their workload. For tax teams, the challenge is to track reforms as they develop while meeting current obligations and preparing for new reporting and scrutiny requirements.
In the meantime, existing rules remain in force. Companies still have to manage tax transparency and administrative cooperation requirements while assessing what proposed changes could mean. Importantly, a change to when information must be provided does not necessarily remove the need to keep evidence supporting a tax position.
That distinction matters. A company may not need to report something at the same stage as before, but it may still need to produce documentation if tax authorities later question a transaction. This raises questions about when a company can consider its position secure and how prepared it is to handle a dispute. Clear records and an understanding of the rationale for transactions can be as important as meeting formal reporting deadlines.
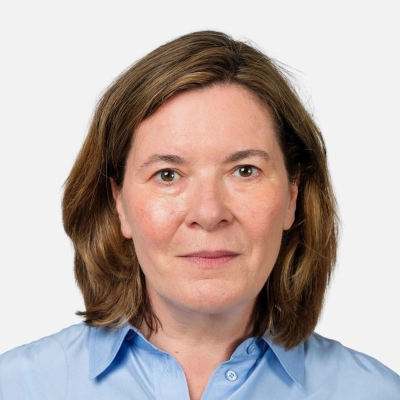
“Legal certainty is key. Tax teams should think beyond filing requirements and consider how they would support their positions if challenged.”
Ivana van der Maas Head of Professional Tax Practice, Forvis Mazars Netherlands
The way tax authorities use information may also change as tax authorities adopt more digital tools, including AI. One developing possibility is that authorities will move away from template-based reporting toward systems that draw information from repositories. This could create uncertainty for taxpayers about what information authorities will access and how it will be analysed.
The practical task is twofold: keep complying with today's rules and assign people to monitor what may change tomorrow. Preserving supporting evidence and preparing for disputes can help organisations navigate reforms without mistaking a promise of simplification for immediate certainty.
Preparing for what’s nextStrengthening global tax compliance in construction and engineering |
The challengeAn international construction and engineering business serving customers in more than 30 countries needed reliable tax compliance support across multiple jurisdictions. Managing differing regulatory requirements demanded strong international knowledge and experience, responsive advice and a consistent approach to addressing tax challenges. The business sought a trusted adviser who could help its tax leadership manage these obligations while supporting its wider growth ambitions. |
Our solutionForvis Mazars worked closely with the company’s tax director to understand its priorities and provide practical, strategic advice on international tax matters. This led to a successful pilot engagement in Latin America, establishing a foundation for broader cooperation. Regular dialogue, responsiveness and access to specialist knowledge helped build a trusted working relationship. |
ImpactThe initial engagement gave the business greater confidence in addressing international tax compliance challenges and provided a foundation for supporting future growth opportunities. The relationship has since developed towards broader coordination across regions and service lines, including potential UK tax and advisory support. By combining international experience with a responsive, collaborative approach, Forvis Mazars helped the business strengthen its ability to navigate regulatory complexity while pursuing its commercial ambitions. |
Move the tax function beyond compliance and reporting to become a proactive adviser on business growth, investment, restructuring, risk management and cash-flow preservation. Ensure reporting is accurate, tax risks are understood by management, and the company can explain its positions to stakeholders and, where relevant, the public. Involve tax leaders early in strategic decisions. Build the tax team’s understanding of operations, forecasts and cash flows so it can support decisions, preserve value and help the business respond to change.
Build the capability to monitor evolving international tax rules, assess geopolitical risks and prepare for potential policy changes. Use scenario planning to strengthen resilience rather than simply reacting to new regulations. Build an integrated, cross-border view of risk. Connect tax with customs, trade, supply chain and sustainability teams, and develop the capability to assess how geopolitical or regulatory changes affect the organisation across jurisdictions.
Ensure tax information is accurate, accessible, consistent and reliable across jurisdictions. Establish clear data ownership and repeatable reporting processes to meet growing compliance and disclosure requirements. Use automation to improve efficiency, with appropriate oversight.
Develop flexible processes, strong cross-functional relationships and clear decision-making responsibilities. Ensure tax teams can respond quickly to regulatory developments, operational changes and emerging business risks without compromising oversight. Stay ahead of policy and regulatory change. Build agility through preparation. Plan for plausible changes, identify information gaps early, and develop the ability to adapt and execute quickly when rules change.
Address skills gaps through continuous professional development, appropriate technology, and stronger relationships with finance, legal, operations, external advisers and industry peers. Combine technical knowledge with commercial judgement and forward-looking insight.

Supporting you to achieve sustainable growth ambitions.

Global regulatory compliance & reporting services that make the complex simple.

Insight and innovation to guide you through today’s evolving global tax landscape.
Tax is operating in an environment of greater scrutiny. Reporting obligations are expanding, transparency is increasing and businesses must navigate regulatory requirements that continue to develop across jurisdictions.

This website uses cookies.
Some of these cookies are necessary, while others help us analyse our traffic, serve advertising and deliver customised experiences for you.
For more information on the cookies we use, please refer to our Privacy Policy.
This website cannot function properly without these cookies.
Analytical cookies help us enhance our website by collecting information on its usage.
We use marketing cookies to increase the relevancy of our advertising campaigns.