
Investing in Southern Europe: why it is emerging as the most attractive destination for international investors
13 October 2026
Tags
Financial services
Private equity
The new report by Forvis Mazars and Mergermarket shows how attractive valuations, entrepreneurial excellence supported by a growing number of generational transitions, and a deep mid-market make Southern Europe and Italy one of the leading “value plays” for international investors.
Southern Europe continues to strengthen its position as a leading destination for mergers and acquisitions, combining economic resilience, political stability and a broad pipeline of investment opportunities. Despite a modest decline in deal volume during the first half of 2026, total announced deal value surged by 37% year-on-year to €147.7bn, highlighting sustained investor confidence and the presence of larger, transformative transactions.
The region's attractiveness is underpinned by three key factors: a robust and often undervalued mid-market, a large population of family-owned businesses entering succession phases, and valuation multiples that remain competitive compared with Northern Europe and the United States.
Key figures
€147.7bn
Total announced M&A value in Southern Europe in H1 2026
1,858 deals
Announced across the region during H1 2026
€61,2 mld
Generated by investors from outside Southern Europe
Southern Europe's leading M&A markets
While Southern Europe shares common strengths, each market offers a distinct investment story. Across the region, strong domestic businesses, increasing cross-border activity and a growing presence of private equity continue to support dealmaking.
Italy was the standout market in the first half of 2026, recording 754 transactions with a total value of €87.1 billion, the highest level seen in the country over the past two decades. Landmark deals across the banking, TMT and pharmaceutical sectors reinforced its position as the leading M&A market in Southern Europe. |
One of Europe’s most attractive destinations for inbound M&A investment, Spain recorded 600 announced transactions with a total value approaching €29 billion. The country continues to strengthen its position as a key hub for AI- and technology-driven investment opportunities. |
Switzerland was the region’s third-largest market, with 221 announced transactions worth a combined €16 billion. It remains a strategic destination for international investors seeking exposure to technology, healthcare and advanced industrial assets. Despite lower deal volumes, Switzerland accounted for three of the ten largest transactions in Southern Europe during H1 2026. |
While deal volumes remained comparatively lower, M&A activity in Türkiye was characterised by significantly larger transaction sizes. Total deal value increased by 74% compared with 2025, reflecting continued investor interest in strategic sectors such as industrials, energy and infrastructure. |
Despite a slowdown in activity during H1 2026, Portugal continues to offer attractive investment opportunities. The country maintains strong prospects across technology, business services, hospitality and the mid-market segment, supported by a dynamic entrepreneurial ecosystem and growing appeal among international investors. |
Greece continues to stand out as one of Southern Europe’s most international markets. Although aggregate deal value declined compared with the previous year, M&A volumes remain at their highest levels in two decades, underlining the resilience, dynamism and ongoing evolution of the market. |
Sector trends shaping the future of dealmaking
M&A activity across Southern Europe is increasingly concentrated in sectors benefiting from long-term structural trends such as digitalisation, healthcare innovation, industrial transformation and changing consumer preferences. While overall deal volumes have softened, transaction values have risen sharply, reflecting increased competition for high-quality assets.
Technology, media and telecommunications (TMT) Technology continues to be one of the most attractive investment themes in the region. Total deal value almost doubled in H1 2026 to €28.4bn, making TMT the second-largest sector by value. AI-enabled businesses, digital infrastructure, software platforms and data-driven technologies are attracting growing investor attention, particularly in Switzerland, Spain and Italy. The sector's largest transaction was Poste Italiane's €21.4bn offer for Telecom Italia (TIM), one of the defining deals of the year. |
Industrials and chemicals Industrials and chemicals remained the most active sector by volume, generating 330 transactions during H1 2026. The sector's value more than doubled year-on-year to €16.4bn, supported by major cross-border acquisitions and ongoing consolidation activity. Southern Europe continues to benefit from a strong manufacturing base, established supply chains and increasing demand for infrastructure, environmental services and industrial technology assets. |
Pharma, medical and biotech Pharmaceuticals, medical and biotech emerged as one of the strongest sectors in terms of transaction value, reaching €19.4bn in H1 2026. Investor interest continues to be fuelled by healthcare innovation, specialised life sciences assets and growing demand for biotechnology capabilities. Large transactions involving Recordati, Lonza and DSM-Firmenich illustrate the region's attractiveness to international investors and private equity firms alike. |
Financial services Financial services generated the highest aggregate deal value among all sectors, reaching €43.5bn. The sector is being reshaped by a wave of consolidation, particularly in banking, as institutions seek greater scale, efficiency and resilience in response to regulatory and operational pressures. Italy was the epicentre of this trend, with several landmark transactions involving Monte dei Paschi di Siena and other leading financial institutions. |
Consumer Consumer M&A remains resilient and is expected to be one of the most active sectors over the coming quarters. Food production, premium brands, hospitality and consumer services continue to attract strategic and financial buyers. Interestingly, the bakery segment emerged as one of the most active subsectors in H1 2026, reflecting changing consumer demand and strong investor appetite for scalable, international consumer brands. Looking ahead, Mergermarket data indicates that consumer assets represent the single largest pool of potential future transactions in Southern Europe. |
Private equity in Southern Europe
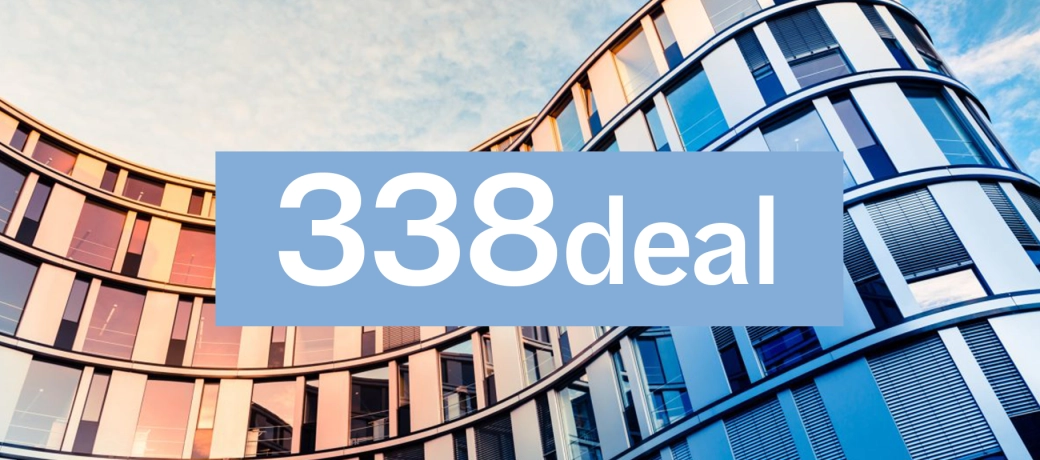
Announced in H1 2026 |
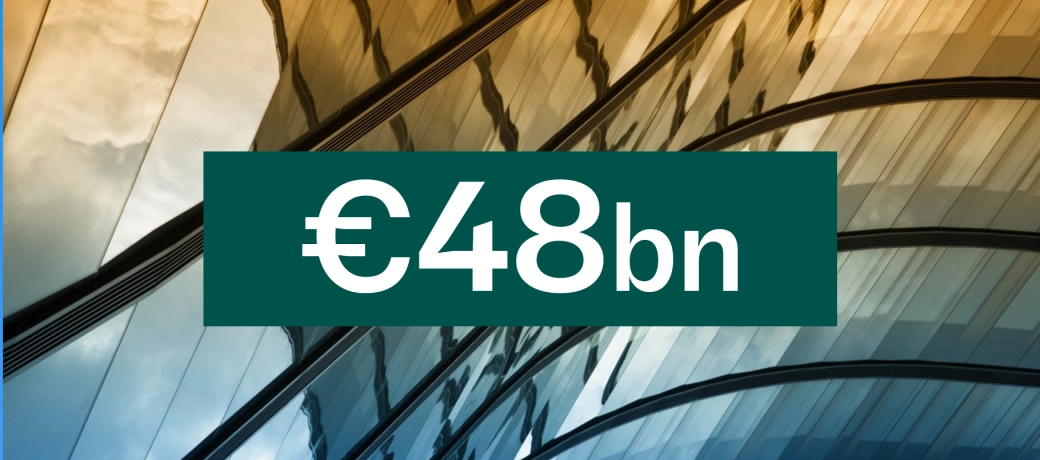
Total private equity deal value |
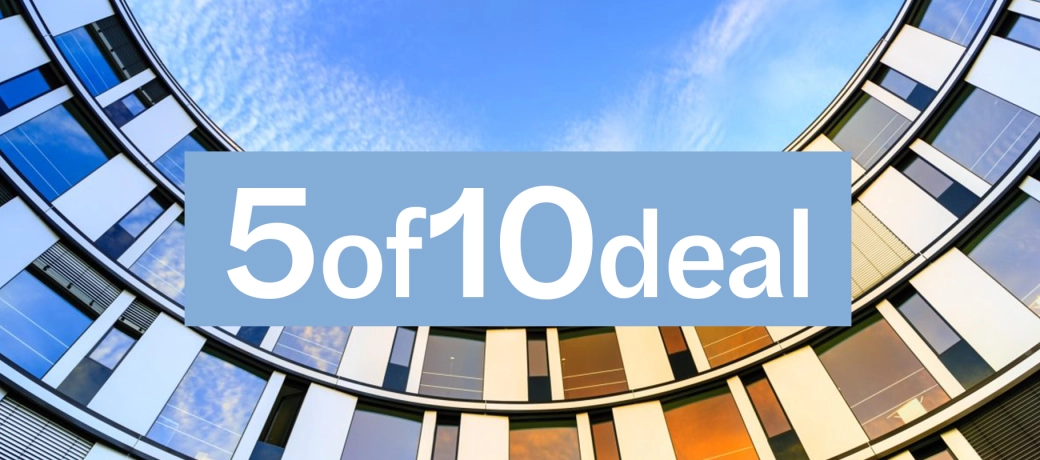
Involved PE investors |
Southern Europe recorded 338 PE deals (comprising buyouts as well as exits) in H1 2026, down 15% compared to H1 2025.
In value terms, PE generated €48bn worth of deal activity in H1. That represents a year-on-year increase of 23%, underlining the impact of a handful of large PE deals. Indeed, the top-10 PE deals of H1 2026 represent more than two-thirds of aggregate PE value, with UK and North American bidders accounting for all but one of the 10 largest transactions.
Competitive valuations are one of the big attractions for inbound acquirers, with Southern Europe typically offering lower entry multiples relative to the US and Northern Europe.
Several structural factors add to the attraction of Southern Europe. These include fragmented sectors that are ripe for buy-and-build, plus a continuing wave of family-owned business successions. To round it off, the region offers an abundance of targets that are a natural draw for global capital – including energy transition, infrastructure, hospitality and tourism-linked assets.
Our experts