Circular 118/2026/TT-BTC: IFRS for Vietnam IFC Members
Download full PDF below.

IFRS transition is more than an accounting conversion. Although it begins with financial reporting requirements, its effects can extend to governance, performance measurement, systems, data and controls. A well-managed transition can improve financial comparability and support better-informed discussions with investors and financing partners. These benefits depend on implementation quality; they are not automatic.
Circular 118 was issued under Clause 5, Article 3 of Decree 324/2025/ND-CP. Circular 118 applies to enterprises and economic organizations that are members of the International Financial Center (IFC) within the scope of Resolution 222/2025/QH15 and related guidance.
Under Circular 118, effective International Accounting Standards must be applied in their original form and consistently throughout the financial year. Commencement or discontinuation is permitted only at the beginning of the subsequent annual accounting period.
Under Circular 118, written notice must be sent to the Ministry of Finance at least 30 days before commencing or discontinuing application. For a 1 January 2027 start, this means early December 2026 at the latest. Financial statements and consolidated financial statements must be submitted to the IFC's Executive Body and Supervisory Body and competent Vietnamese authorities. Reporting periods, filing deadlines and public disclosure remain subject to applicable Vietnamese requirements.
Entities applying the standards under Circular 118 are responsible for their election and must provide complete information and clear explanations to tax, regulatory and supervisory authorities. They must also include a statement of compliance in the notes to their financial statements and consolidated financial statements.
Circular 118 does not replace tax legislation: tax obligations continue to be determined under Vietnamese tax law. The implementation team should separately assess current and deferred tax consequences and maintain clear reconciliations between financial reporting and tax information.
A common reporting framework can make financial information easier to compare across entities and markets. For management, the opportunity of a common reporting framework is to improve the quality of information used in decisions and strengthen communication with stakeholders.
Management key performance indicators (KPIs) also need consistent definitions and reconciliations to IFRS measures. Under IFRS 18, certain management-defined performance measures (MPMs) must be disclosed and reconciled in the notes.
Technical accounting, project governance, and data readiness need to be addressed together. We recommend five foundations:
Policies must follow IFRS requirements and reflect the entity's transactions and operating model. Business objectives inform implementation priorities, not departures from accounting requirements. Document permitted choices and significant judgements.
Appoint an executive sponsor and finance project lead. Involve operations, information technology (IT), treasury, human resources (HR) and tax specialists as relevant, with named owners for data, technical decisions and controls.
Include policy approval, the opening IFRS statement of financial position, comparative information, system readiness, draft disclosures and pilot reporting. Build regulatory notification and filing requirements into the project calendar.
Depending on the business, prioritize revenue, leases, financial instruments, impairment, income taxes, employee benefits, consolidation and presentation under IFRS 18, which applies from 2027. Escalate material judgements and data gaps before they affect the reporting timetable.
Keep the board or members' council, lenders and other relevant stakeholders informed about progress, unresolved issues and material changes in reported results. Distinguish accounting changes from changes in underlying business performance.
Phase 1 starts with accounting differences and follows the supporting processes, data and controls end to end. Typical Viet Nam differences include:
Area | Typical difference | Standard |
| Statutory severance allowances | Often accounted for as defined benefit obligations | IAS 19 |
| Operating leases | Brought onto the balance sheet | IFRS 16 |
| Credit losses | Expected credit losses replacing Vietnamese Accounting Standards (VAS) provisioning | IFRS 9 |
| Goodwill | Tested for impairment rather than amortised | IAS 36 |
| Functional currency | Functional currency determination | IAS 21 |
The output of Phase 1 should be a prioritized action plan, with owners, data requirements and decision deadlines.
First-time adoption requires a separate workstream. Circular 118 requires entities changing accounting frameworks to present comparative information and full disclosures under IFRS 1. IFRS 1 requires:
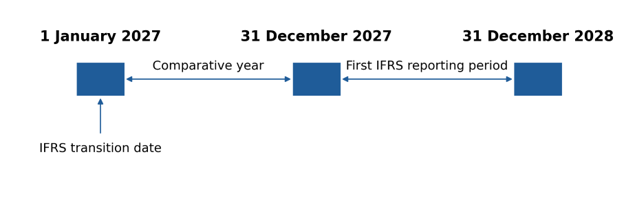
Under IFRS 1, the first IFRS financial statements include at least three statements of financial position, including the opening one.
Illustration, not a prescribed deadline: for an existing calendar-year entity whose first IFRS financial statements are for the year ending 31 December 2028, with one full comparative year, the transition date is 1 January 2027 and the comparative year is 2027.
The Circular’s effective date is not automatically the IFRS transition date; management must determine the timeline from the first reporting period and comparative information presented.
Implementation (Phase 3) turns policy decisions into repeatable operations. Entities should:
System enhancements and process redesign may be needed depending on volume and complexity. Controlled spreadsheets can support the IFRS transition, but should have defined ownership, version control, reconciliations, and review.
Training & Monitoring (Phase 4) embeds IFRS into monthly and quarterly routines. Pilot closes, targeted workshops and structured reviews help teams apply policies consistently. Management should monitor unresolved judgements, data quality, reporting timeliness and control exceptions, with clear escalation and corrective actions.
For eligible IFC members considering the election under Circular 118, we recommend completing an IFRS readiness assessment before committing to a reporting timetable. Confirm eligibility with the appropriate specialists, define the first reporting period and transition date, and assess accounting gaps, data, systems, controls and resources. Use the results to approve a phased roadmap, assign accountable owners and plan notification and filing obligations.
Contact our Accounting & Outsourcing team to discuss how Circular 118 applies to your IFRS transition strategy in Vietnam.
(*) Circular 118 uses "International Accounting Standards" as its regulatory term. This article uses "IFRS Accounting Standards" or "IFRS" when discussing the financial reporting framework and first-time adoption under IFRS 1. In our view, the Circular's term should be read as the full body of standards issued by the International Accounting Standards Board (IASB) (IFRS, IAS and Interpretations), not only the standards titled "IAS".
*Disclaimer: The materials presented by Forvis Mazars in Vietnam have been prepared for the purpose of providing professional updates in Vietnam. The information, analyses, and comments contained herein are intended solely as general guidance and are based on, cited from, and interpreted from official regulations and documents issued by government authorities. We recommend that clients contact Forvis Mazars Vietnam's advisory team for detailed professional advice tailored to their specific circumstances.
Download full PDF below.


On 18 August 2026, the Ministry of Finance issued Circular No. 118/2026/TT-BTC on the eligible entities, scope, and manner of applying International Accounting Standards (*) in Viet Nam. Circular 118 establishes an election for eligible members of the International Financial Center in Viet Nam (the IFC), not a general mandate to apply International Financial Reporting Standards (IFRS) for all Vietnamese...
The Government has issued six key decrees implementing the new construction law framework, all effective from 1 July 2026. These decrees form the core implementing framework of Vietnam’s new construction regime and introduce substantial changes affecting the development, procurement, execution and management of construction projects. The six decrees are Decree No. 206/2026/ND-CP, Decree No. 207/2026/ND-CP,...
Vietnam has elevated AI within a broader industrial and digital capability agenda through Decision 1131/QD-TTg (11 strategic technology groups and 35 strategic technology products) and enacted its first standalone Law on Artificial Intelligence (Law No. 134/2025/QH15) on 10 December 2025, effective 1 March 2026, introducing a risk-based classification concept (high/medium/low). This article summarizes...

This guide sets out how venture capital (VC) firms and crypto funds should approach digital asset valuation as Vietnam moves toward a licensed, onshore digital asset market. It covers the principal categories of digital assets, from cryptocurrencies to stablecoins, the valuation methodologies suited to each, and the Quantity Theory of Money (QTM) as a strategic framework for analyzing tokenomics.
On 27 October 2025, the Ministry of Finance officially issued Circular 99/2025/TT-BTC ("Circular 99") providing guidance on the corporate accounting regime. The Circular has been effective since 1 January 2026 and applies to financial years beginning on or after that date. Vietnamese enterprises should now ensure that their accounting policies, systems and reporting processes reflect the new requirements.
This website uses cookies.
Some of these cookies are necessary, while others help us analyse our traffic, serve advertising and deliver customised experiences for you.
For more information on the cookies we use, please refer to our Privacy Policy.
This website cannot function properly without these cookies.
Analytical cookies help us enhance our website by collecting information on its usage.
We use marketing cookies to increase the relevancy of our advertising campaigns.