22 Sept 2026
EU VAT refund 30 September deadline
Irish businesses have until 30 September 2026 to reclaim eligible VAT incurred in other EU Member States during 2025.

As Budget 2027 approaches, there is an opportunity to introduce property tax measures that support housing delivery, improve affordability, stimulate investment and encourage more efficient use of existing housing stock.
This article outlines a number of proposals that could help address these challenges. In particular, Budget 2027 should consider measures to:
Much of the policy focus in recent years has been on supporting purchasers of newly built homes. However, a significant proportion of first-time buyers acquire second-hand properties, often facing substantial upfront costs in the process.
A targeted stamp duty exemption for first-time buyers purchasing second-hand homes would reduce barriers to entry and support broader access to home ownership. Such a measure would recognise the important role that existing housing stock plays in addressing housing demand.
The Help to Buy scheme has successfully assisted many first-time buyers purchasing newly constructed homes. Consideration should now be given to extending the scheme to second-hand residential properties, thereby broadening access to support and reflecting the realities of the current housing market.
The Mortgage Interest Tax Credit has provided valuable support for homeowners impacted by higher interest rates. While the relief has been extended to cover the 2025 and 2026 tax years, consideration should be given to extending support beyond 2026 where mortgage costs remain materially above historical norms.
Any future extension should also include a review of the current eligibility criteria to ensure that more recent purchasers are not unfairly excluded from relief.
Increasing housing supply is not solely about delivering new homes. Bringing vacant and derelict properties back into productive use must also form part of the solution.
A targeted capital gains tax relief, or reduced capital gains tax (CGT) rate, for refurbished derelict properties could encourage investment in regeneration projects and support the revitalisation of town centres, villages and urban communities while delivering additional housing supply.
Improving the energy efficiency of Ireland's housing stock remains a key policy objective.
A dedicated tax credit linked to measurable improvements in a property's Building Energy Rating (BER) could encourage greater investment in retrofit activity, support climate objectives and help homeowners offset a portion of the significant costs associated with energy-efficiency upgrades.
Housing delivery cannot be accelerated without corresponding investment in critical infrastructure.
Continued investment in water services, electricity networks and public transport infrastructure is essential if housing targets are to be achieved. In parallel, further support for modern methods of construction could help increase productivity, reduce build times and improve overall delivery capacity across the residential sector.
The abolition of RZLT regime would be one of a package of measures aimed at rewarding and facilitating development rather than penalising land hoarding. It could assist housing delivery by reducing costs, complexity and risk for developers.
Alternative measures could be introduced to ensure that serviced, residentially-zoned land is actively developed rather than held indefinitely. Such measures could include the introduction of a CGT Rollover Relief for Housing Development and an exemption from tax for profits reinvested into construction of residential property.
Development levies continue to represent a significant cost for many residential projects.
A temporary and targeted waiver or reduction in development levies could help improve project viability and support the commencement of housing developments that might otherwise be delayed or deferred.
Planning delays continue to create uncertainty for developers, investors and prospective homeowners.
Further resourcing of planning authorities and targeted reforms aimed at improving efficiency would help accelerate housing delivery and provide greater certainty throughout the development lifecycle.
Many towns and cities contain commercial buildings that are no longer suited to modern business requirements but could be repurposed to provide much-needed residential accommodation.
Targeted tax incentives to encourage commercial-to-residential conversion projects could unlock additional housing supply, support urban regeneration and make more efficient use of existing building stock.
The enhanced corporation tax deduction for qualifying apartment construction costs introduced by Finance Act 2025 was a welcome development. However, uncertainty remains regarding the interaction between section 81E TCA 1997 and the definition of an "excepted trade" in section 21A TCA 1997. This may limit the practical availability of the enhanced deduction for certain refurbishment and conversion projects. Clarifying these provisions would help ensure that genuine regeneration projects can fully benefit from the relief and would strengthen the effectiveness of the regime.
Property values have increased significantly over recent years, while relevant tax thresholds have not always kept pace.
A review of Capital Acquisitions Tax (CAT) group thresholds, together with a broader review of capital taxes affecting property transfers, could facilitate intergenerational transfers and support greater mobility within the property market.
Housing availability has increasingly become a labour market and competitiveness issue.
In several sectors, employers face recruitment and retention challenges arising directly from housing shortages and affordability concerns.
Consideration should be given to introducing a dedicated capital allowances regime, modelled on the former industrial buildings allowance framework, for employers who develop accommodation for their workforce.
Such a measure could encourage private sector investment in employee housing, increase overall housing supply and provide businesses with a practical tool to address recruitment challenges.
Some employers have already begun providing subsidised accommodation to support employee recruitment and retention.
A targeted benefit-in-kind (BIK) exemption for employer-provided accommodation, particularly for lower-income employees or workers employed in sectors experiencing acute labour shortages, could improve labour mobility, reduce affordability pressures and strengthen Ireland's attractiveness as a location for investment and employment.
A healthy rental market remains an essential component of Ireland's housing system. However, rising costs and increasing regulatory burdens have contributed to a continued reduction in private rental supply.
To encourage long-term investment and participation in the sector, Budget 2027 should consider a range of targeted reforms.
First, broader business taxation principles could be applied to professional landlords, allowing a wider range of legitimate rental expenses to be deducted when calculating taxable profits.
Second, consideration should be given to extending the 12.5% corporation tax trading rate to qualifying professional corporate landlords. While rental income is currently subject to corporation tax under the passive income rules, a review of the current treatment could help encourage long-term institutional investment in the sector.
Finally, amendments should be made to the landlord relief provisions introduced in recent Finance Acts to prevent unintended clawback consequences where a property is transferred between spouses or civil partners and continues to be rented. Such a change would allow the relief to operate in accordance with its apparent policy objectives.
The Rent Tax Credit has become an important support for many households facing elevated rental costs.
Removing the current sunset clause and placing the credit on a permanent footing would provide greater certainty for tenants while recognising the ongoing affordability challenges faced across the rental market. Consideration could also be given to progressively increasing the value of the credit over time.
There is no single measure capable of resolving Ireland's housing challenges. However, a combination of targeted tax incentives, infrastructure investment and regulatory reform could play a significant role in increasing housing supply, improving affordability and stimulating investment.
As policymakers finalise the measures to be included in Budget 2027, there is a clear opportunity to introduce practical reforms that support housing delivery, encourage regeneration, strengthen the rental sector and improve access to home ownership.
Given the scale of Ireland's housing challenge, property and housing policy should remain at the centre of the Budget 2027 agenda.
Irish businesses have until 30 September 2026 to reclaim eligible VAT incurred in other EU Member States during 2025.
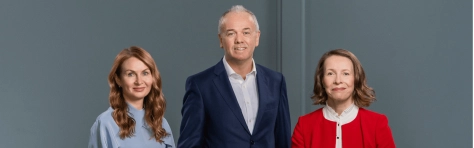
Forvis Mazars is pleased to announce the appointments of Oonagh Carney as Partner and Head of Indirect Tax Services and Elaine Daly as Partner and Head of Business Consulting.
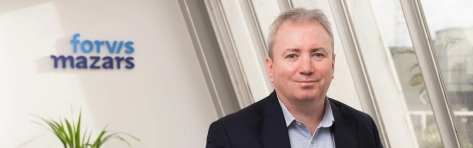
Gerry Vahey, Partner and Head of Tax, was recently interviewed and featured in Business Plus. You can find the full text of the article below.
Insight and innovation to guide you through an ever-evolving tax landscape.

Strategies and solutions to help you stay compliant in an evolving environment.

The rising importance of VAT and indirect taxes demands a proactive, strategic approach.

Smart independent tax advice for senior executives, business owners and high net-worth individuals.

Efficiently managing complexity in an evolving tax landscape.
This website uses cookies.
Some of these cookies are necessary, while others help us analyse our traffic, serve advertising and deliver customised experiences for you.
For more information on the cookies we use, please refer to our Privacy Policy.
This website cannot function properly without these cookies.
Analytical cookies help us enhance our website by collecting information on its usage.
We use marketing cookies to increase the relevancy of our advertising campaigns.